AI-Powered
Loan Origination & Credit Decisioning

Digitize application intake, supporting documents, KYC and income verification, credit and collateral assessment, underwriting summarization and decision routing across the lending journey.

Business challenge

Manual Document Review and Risk Checks Extend Credit Decision Cycles

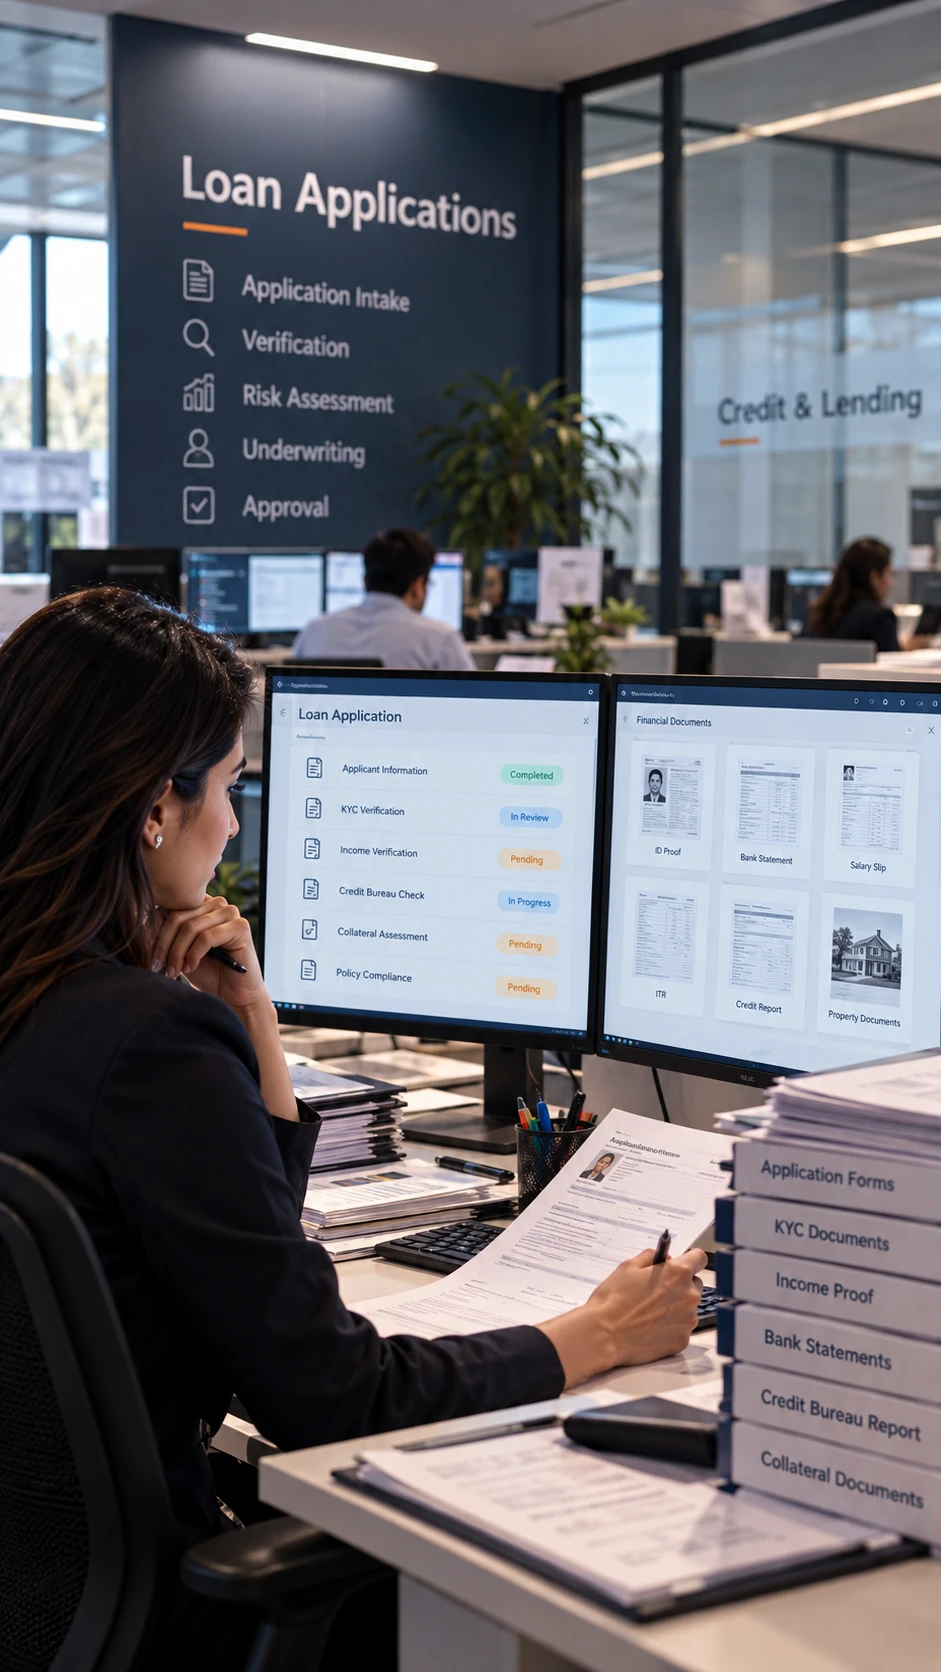
Loan origination requires lenders to collect application evidence, validate identity and income, retrieve bureau information, assess policy fit and collateral, document the rationale and route decisions through the appropriate authority. Sequential manual processing increases turnaround time, cost and inconsistency, especially for lower-risk cases that do not require deep underwriting.

Common challenges include:

  • Document-intensive intake: Supporting documents need to be collected and associated with the correct application before assessment can begin.
  • Verification workload : KYC and income information must be checked against the application and relevant policy requirements.
  • Multiple risk inputs: Credit bureau information, financial data and collateral details need to be considered together during assessment.
  • Underwriter preparation effort:Risk findings and supporting evidence must be consolidated into a clear case before human review.
  • Decision consistency: Policy rules, verification results and credit context need to be presented consistently so comparable applications can be reviewed on a common basis.

Straight-Through Credit Orchestration with Risk-Based Exception Routing

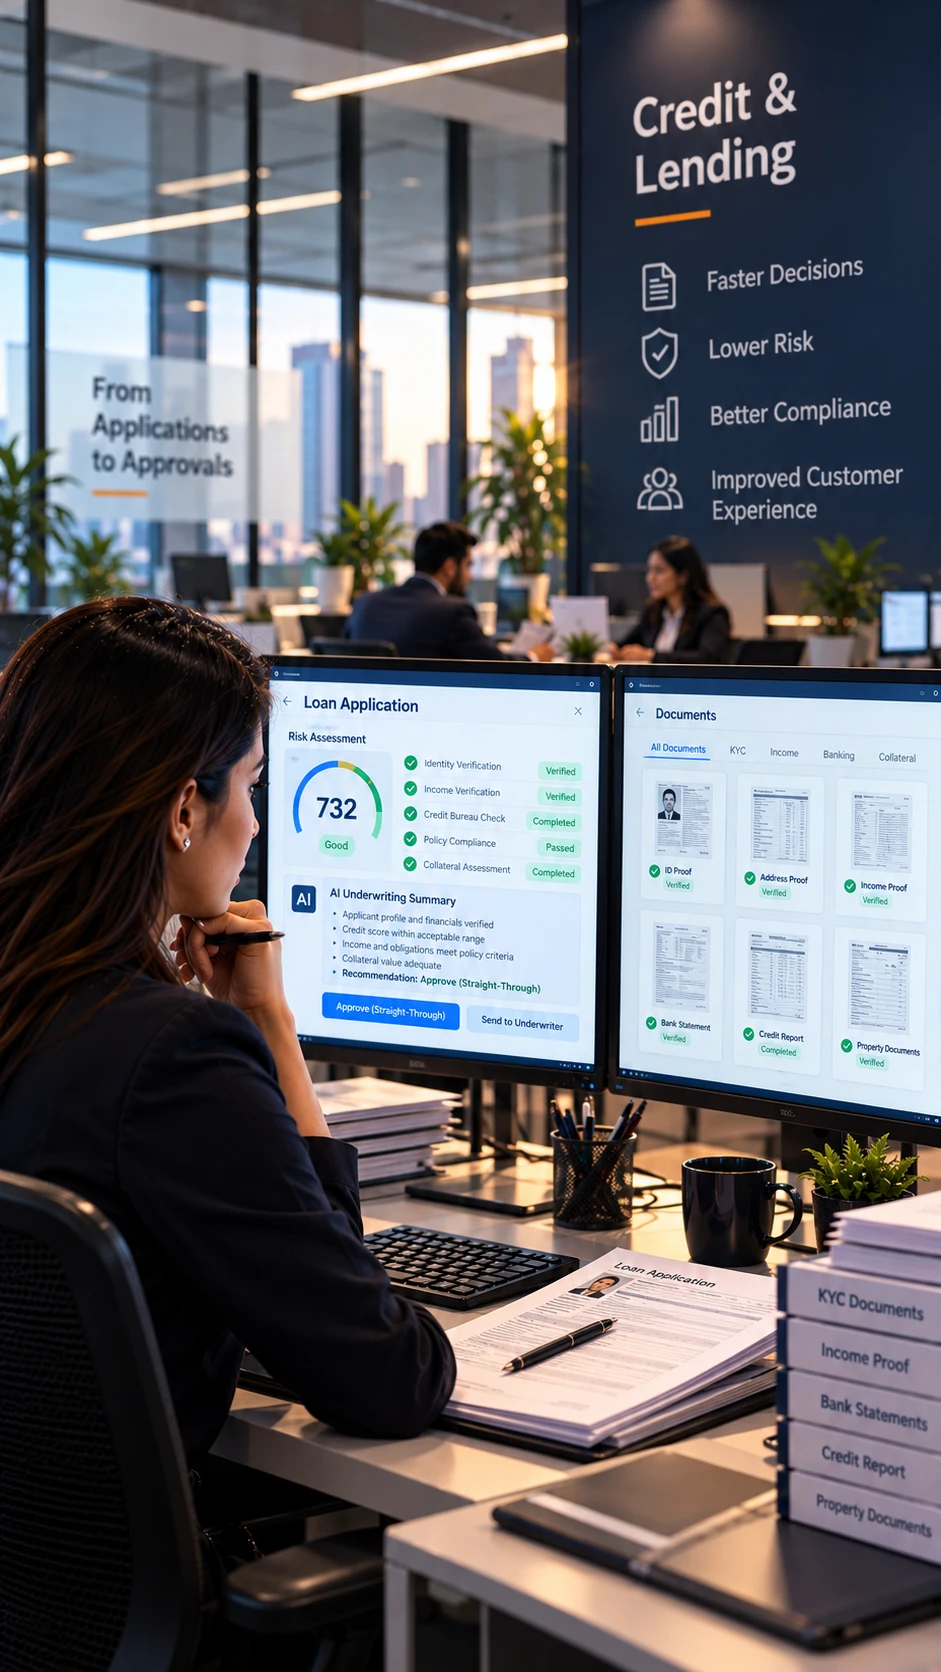
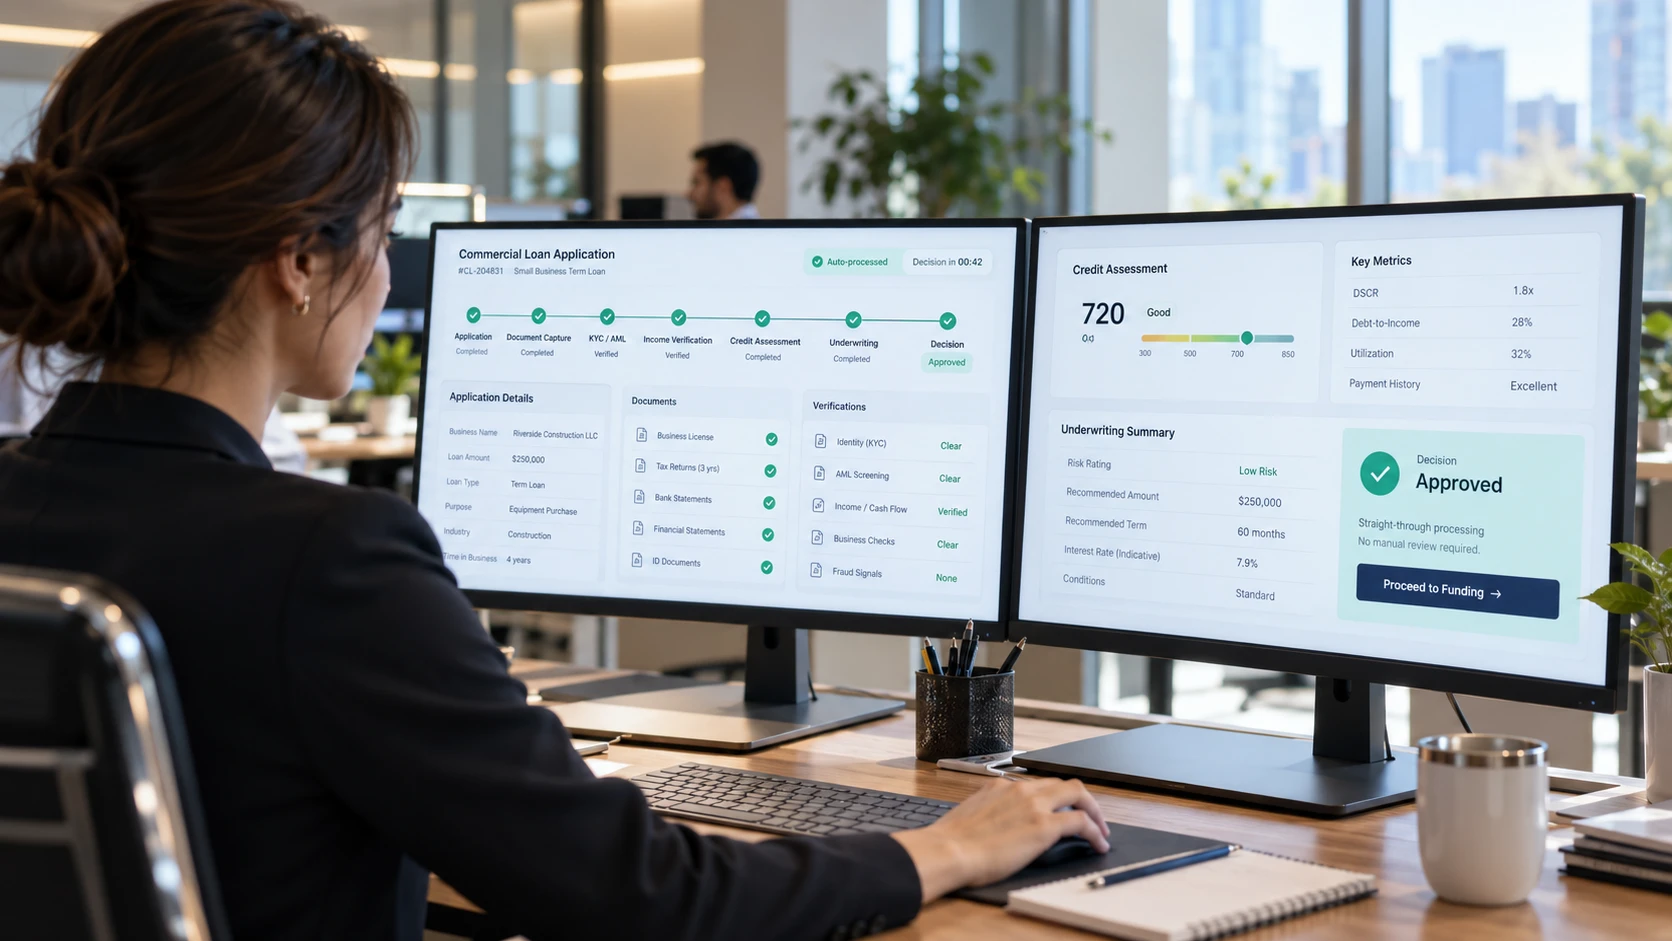
The workflow captures and validates supporting documents, performs KYC and income checks, applies policy and credit scoring, assembles a structured underwriting summary and routes the case based on risk and authority thresholds. Straight-through cases can progress automatically, while underwriters retain decision control for exceptions and higher-risk applications.

The solution uses:

  • Automated application intake: Create a consistent starting point for new loan applications and establish the case record.
  • Supporting-document capture: Collect and organize KYC, income, banking and collateral documents through intelligent document processing.
  • KYC and income verification: Apply defined checks and rules to validate identity and income information.
  • Credit and collateral assessment: Bring credit data, financial information and collateral context into a structured scoring and review step.
  • AI-generated underwriting summary: Convert application, verification and assessment findings into a concise underwriter-ready brief.
  • Human underwriter review: Keep credit judgment and final decision authority with the underwriter.
  • Decision and notification: Record the confirmed action and current status in the relevant case-management systemRecord the confirmed decision and route it through the LOS or core-system workflow.
Smarter invoice processing solution

Quantified Evidence for Straight-Through Credit Decisioning
Results

70% straight-through loan processing

A bank achieved straight-through processing for 70% of loans after automating data capture and improving the decision engine.

70% lower origination cost

The same lending transformation reduced cost of origination by 70%.

<1 min decision time

Qualifying lending decisions were reduced to under one minute.

From Sequential Loan Processing to
Risk-Segmented Credit Decisioning

The lending journey shifts from uniform manual review toward risk-segmented processing. Routine data capture and policy checks are automated, decision context is prepared consistently and underwriter capacity is concentrated on cases where judgment materially affects risk.

    The workflow

    How AI-Powered Loan Origination & Credit Decisioning Works

    The workflow moves from application intake and intelligent document capture through KYC/income validation, credit assessment, AI-assisted underwriting summary, underwriter review and LOS/core-system decision update..

    01 INTAKE

    Application Intake

    A new loan application enters the workflow and the core borrower and product context is established.

    • Loan application details
    • Applicant or relationship context
    • Requested product and amount

    Technology / System: Application / LOS Intake

    02 CAPTURE

    Capture Supporting Documents

    Required application documents are collected and associated with the correct loan case.

    • KYC documents
    • Income statements and bank statements
    • Collateral or supporting records

    Technology / System: IDP / Supporting Documents

    03 VERIFY

    KYC & Income Verification

    Identity and income information are checked against the application and defined lending rules.

    • KYC information
    • Income and banking evidence
    • Policy and verification requirements

    Technology / System: KYC + Income Validation

    04 ASSESS

    Credit / Collateral Assessment

    Credit and collateral information is assessed to create a structured view of application risk.

    • Credit bureau data
    • Collateral details
    • Policy rules and assessment criteria

    Technology / System: Credit Scoring / Collateral Analytics

    05 SUMMARIZE

    GenAI Underwriting Summary

    Generative AI organizes the application, verification and assessment findings into a concise underwriting brief.

    • Applicant and loan summary
    • Verification outcomes
    • Credit, collateral and policy context

    Technology / System: GenAI Underwriting Summary

    06 REVIEW

    Underwriter Review

    The underwriter reviews the full case and applies lending judgment before confirming the decision.

    • Approve, decline or refer
    • Adjust conditions where required
    • Request additional information or escalation

    Technology / System: Underwriter Review / Authority Matrix

    07 DECIDE

    Decision & Notification

    The confirmed decision is recorded and routed through the loan origination or core-system process.

    • Decision status
    • Conditions or next steps
    • Applicant / relationship-manager notification

    Technology / System: LOS / Core Banking Decision Update